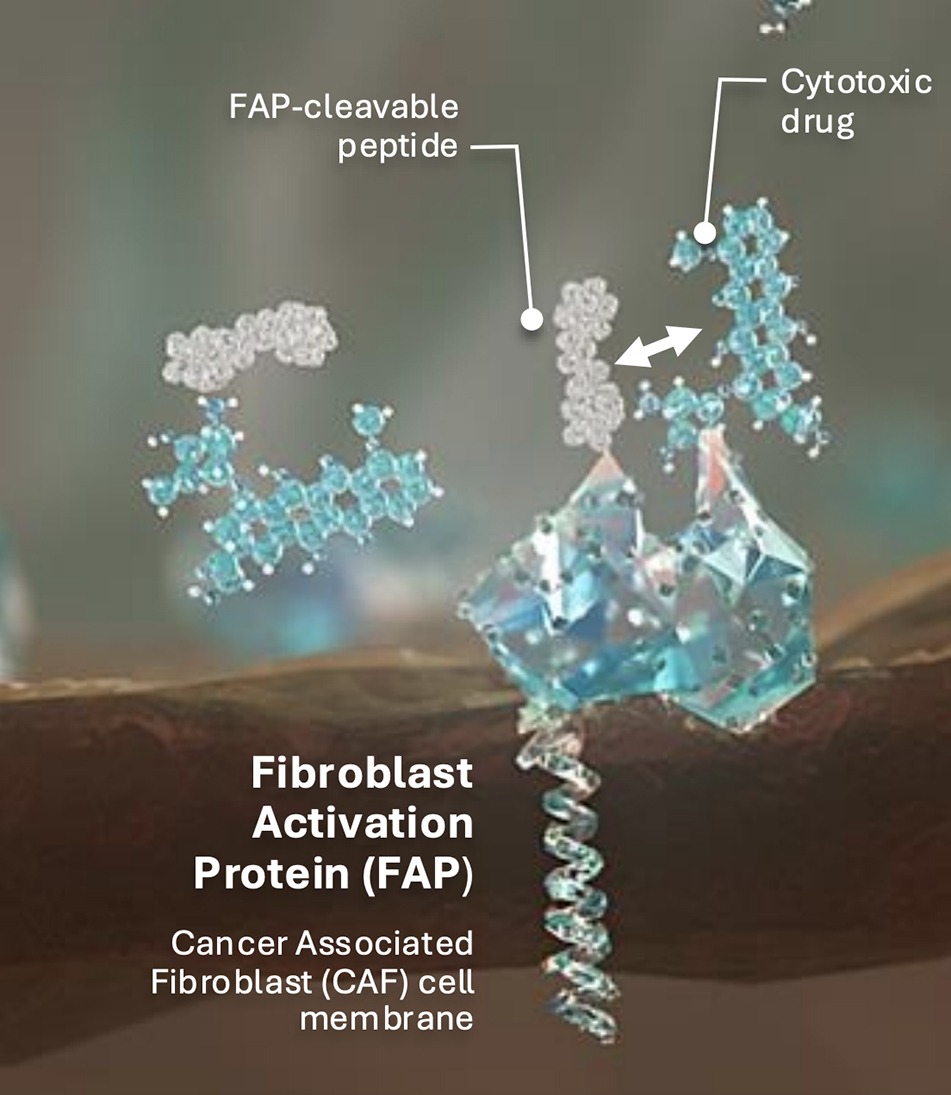
Avacta, a UK-based clinical stage biotech, is differentiated clinical-stage oncology specialist, increasingly defined by continuing progress with its second-generation pre|CISION tumour-activated Peptide Drug Conjugate (PDC) platform.
The lead Gen Two programme, AVA6103 (FAP-EXd, an FAP-activated, controlled-release exatecan), has delivered initial Phase Ia safety and pharmacokinetic data from the FOCUS-01 trial.
These data provide early human validation that the platform successfully replicates the targeted tissue localisation seen in preclinical models. They show a three-fold reduction in systemic payload exposure compared to market-leading antibody-drug conjugate (ADC) benchmarks and avoid the severe myelosuppression typically associated with free topoisomerase I inhibitors. Further clinical news flow over the next 12 months should establish the utility, positioning, and value of the pre|CISION platform.
Initial FOCUS-01 data confirm pre|CISION kinetics Preliminary phase Ia safety and pharmacokinetic data for the lead Gen Two programme, AVA6103, provide the first human validation of the optimised FAP-activated platform. Initial escalation cohorts demonstrate a three-fold reduction in systemic payload exposure compared to existing antibody-drug conjugate benchmarks. While these findings remain exploratory, they indicate that the engineered capping group successfully anchors the parent conjugate within the tumour microenvironment (TME) to create a localised, slow-release reservoir.
FOCUS-01 phase Ib expansion to provide first efficacy data phase Ia dose escalation is continuing through the remaining cohorts, with full safety findings expected by late-2026. The phase Ib portion of the study, planned for early-2027 across six high-prevalence solid tumour indications, is structured to evaluate objective response rates and disease control in these indication-specific cohorts, with initial efficacy data expected to emerge in H127. This transition would represent a critical milestone should pre|CISION translate its pharmacokinetic safety margins into measurable clinical utility.
Proof of mechanism data prompts us to revisit assumptions for our pre|CISION platform valuation given potential for pipeline expansion with multiple payloads addressing the wider 90% of FAP-expressing solid tumours. Cash of £16.4 million at end-April 2026 provides a runway into Q127, covering several value inflection points. Future funding options include licensing/partnering deals, an additional NASDAQ listing, and further equity raises. Our rNPV model values Avacta at £525 million or 111p/share (105p fully diluted) vs £475 million or 101p per share (94p fully diluted) previously.
Trinity Delta only produces research that falls under the non-monetary minor benefit group in MiFID II. We do not seek payment from the asset management community and do not have any execution function, which means you will be able to continue receiving our research under the new MiFID II regulations. To date, all compliance teams at our asset management readers have confirmed that they are satisfied that they can continue to receive our research.
Trinity Delta is a leading provider of issuer-paid equity research for the healthcare and life sciences sectors. We have an experienced, integrated team of analysts providing the highest quality services to companies and to investors. Its expertise in biotech, medtech, specialty pharma and consumer health sectors enable a deep understanding of our clients and their ambitions, which is translated into accessible, impactful and timely research, clearly outlining the investment case.